All Categories
Featured
Navigating 2026 Financial Hardship Help for Families

Expert Reviews of 2026 Debt Consolidation Options
Comparing the Top 2026 Debt Settlement Options
Table of Contents
Home mortgages aren't easy to knock out overnight. However it's a noble financial objective to prioritize settling your mortgage early and owning your house outright. Here are a couple methods you can go over with your bank to see if they make good sense. Recasting allows you to make a lump-sum payment towards your principal and ask your loan provider to re-amortize the loan.
Many lending institutions just charge a small admin cost for this. Refinancing may make good sense if rates fall far enough in 2026. Simply ensure to run the mathematics on closing expenses and your break-even timeline-- specifically if you do not prepare to stay in the home long term. Either strategy can assist maximize regular monthly cash circulation, which you can put straight back into primary paydown or other financial objectives.
That's where a non-profit credit counseling agency can help. (NFCC) offer: Free or inexpensive one-on-one guidanceHelp creating customized financial obligation benefit plansNegotiating assistance with lendersAccess to structured Debt Management Plans (DMPs), where you make a single regular monthly payment and the company pays your creditors directlyHonestly, I've spoken with people that work for these non-profits and they are life-savers.
There's no magic technique to totally eliminate your financial obligation. It takes hard work, conserving cash, and making consistent payments. Others-- like balance transfer cards-- give you a head start by dropping interest rates to 0% for a duration and letting you put every dollar towards development.
These programs include: Internal revenue service Fresh Start programIncome-driven student loan repaymentStudent loan impairment dischargePublic service loan forgivenessIf you qualify, these programs can assist you get out from under unaffordable financial obligation. There are no government financial obligation relief programs for credit card balances.
Best Debt Management Strategies to Eliminate DebtShould You Consolidate Your Debt in 2026?
Can the government help with your debt? There are a couple of various methods the federal government might help make your financial obligation more manageable.

Take the time to review the federal government debt relief choices described listed below to see if you may certify.
Internal revenue service financial obligation relief choices consist of: Pay in time: You can use to the internal revenue service to establish an installment payment plan instead of having to pay at one time: This is a worked out settlement to pay less than the complete amount you oweCurrently not collectible: If the internal revenue service identifies you can not pay your financial obligation at this time, they might accept postpone collection up until you are much better able toPenalty reduction: The internal revenue service might agree to waive specific charges if you took steps to adhere to the rules however didn't pay due to aspects beyond your control.
If you can not manage to pay your state earnings taxes, reach out to your state's department of tax. Income-driven repayment plans are designed to make your trainee loan payments more budget friendly. They do this by basing your month-to-month payments on just how much money you make. There are 4 kinds of income-driven trainee loan repayment strategies: Conserve on a Prized Possession Education (SAVE): This was formerly the REPAYE Strategy.
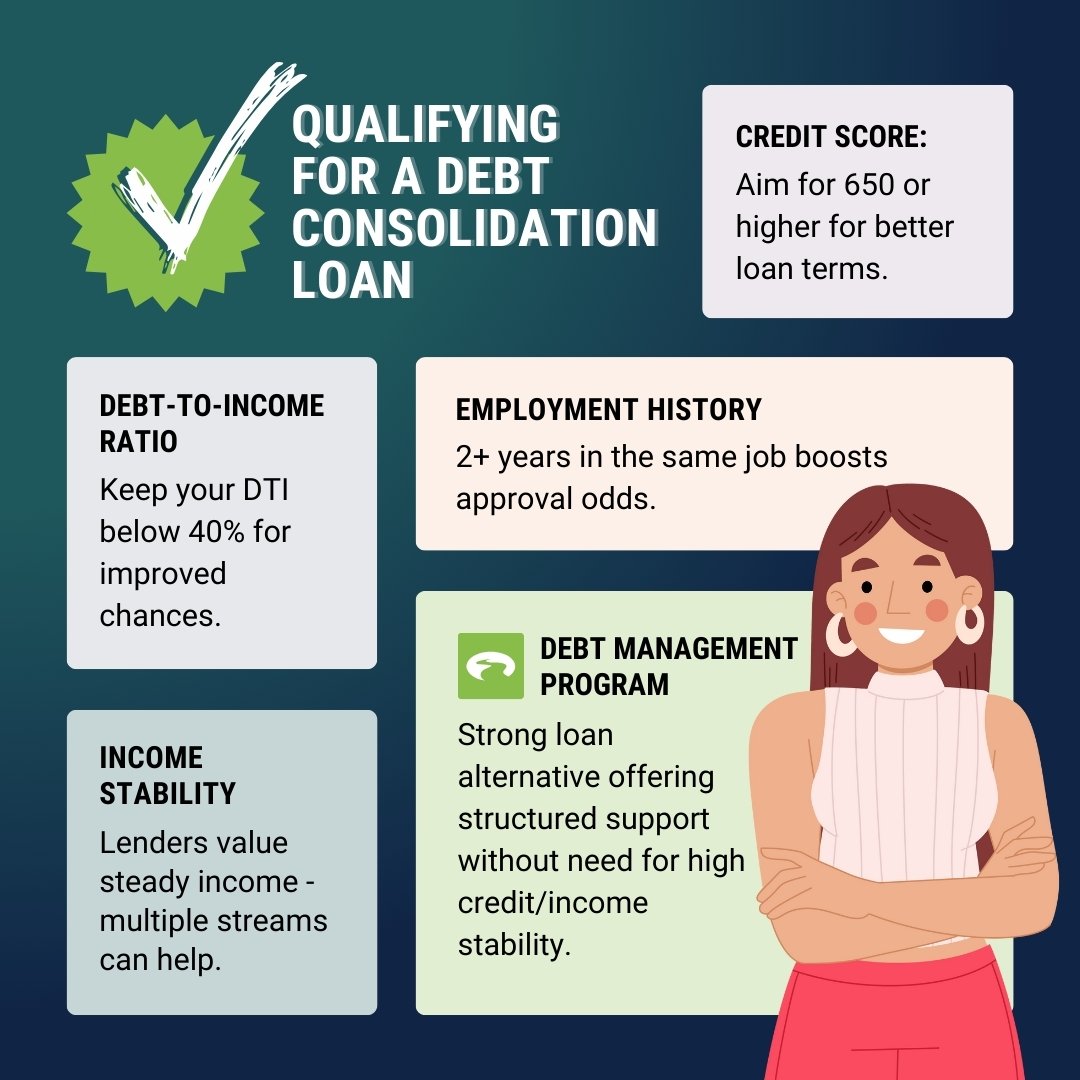
Forgives remaining debt after 20 to 25 years. Forgives remaining financial obligation after 20 years.
Proven Tips to Manage 2026 Debt Stress
Forgives remaining debt after 25 years. Note that these strategies undergo alter over time. Some of these payment strategies may become not available to new borrowers in 2026. Take a look at the government's Trainee Aid website for the newest information. Even for those who certify, these plans are not automatic.
Credentials for these programs depends upon your financial circumstances, what kind of loan you have and when you borrowed it. See the website for details on your eligibility. If you have federal student loans and you end up being completely and completely disabled, you might be able to get your loans released.

Latest Posts

Navigating 2026 Financial Hardship Help for Families
Reducing Household Debt with New Relief Tools
Expert Insights into New Debt Relief Frameworks